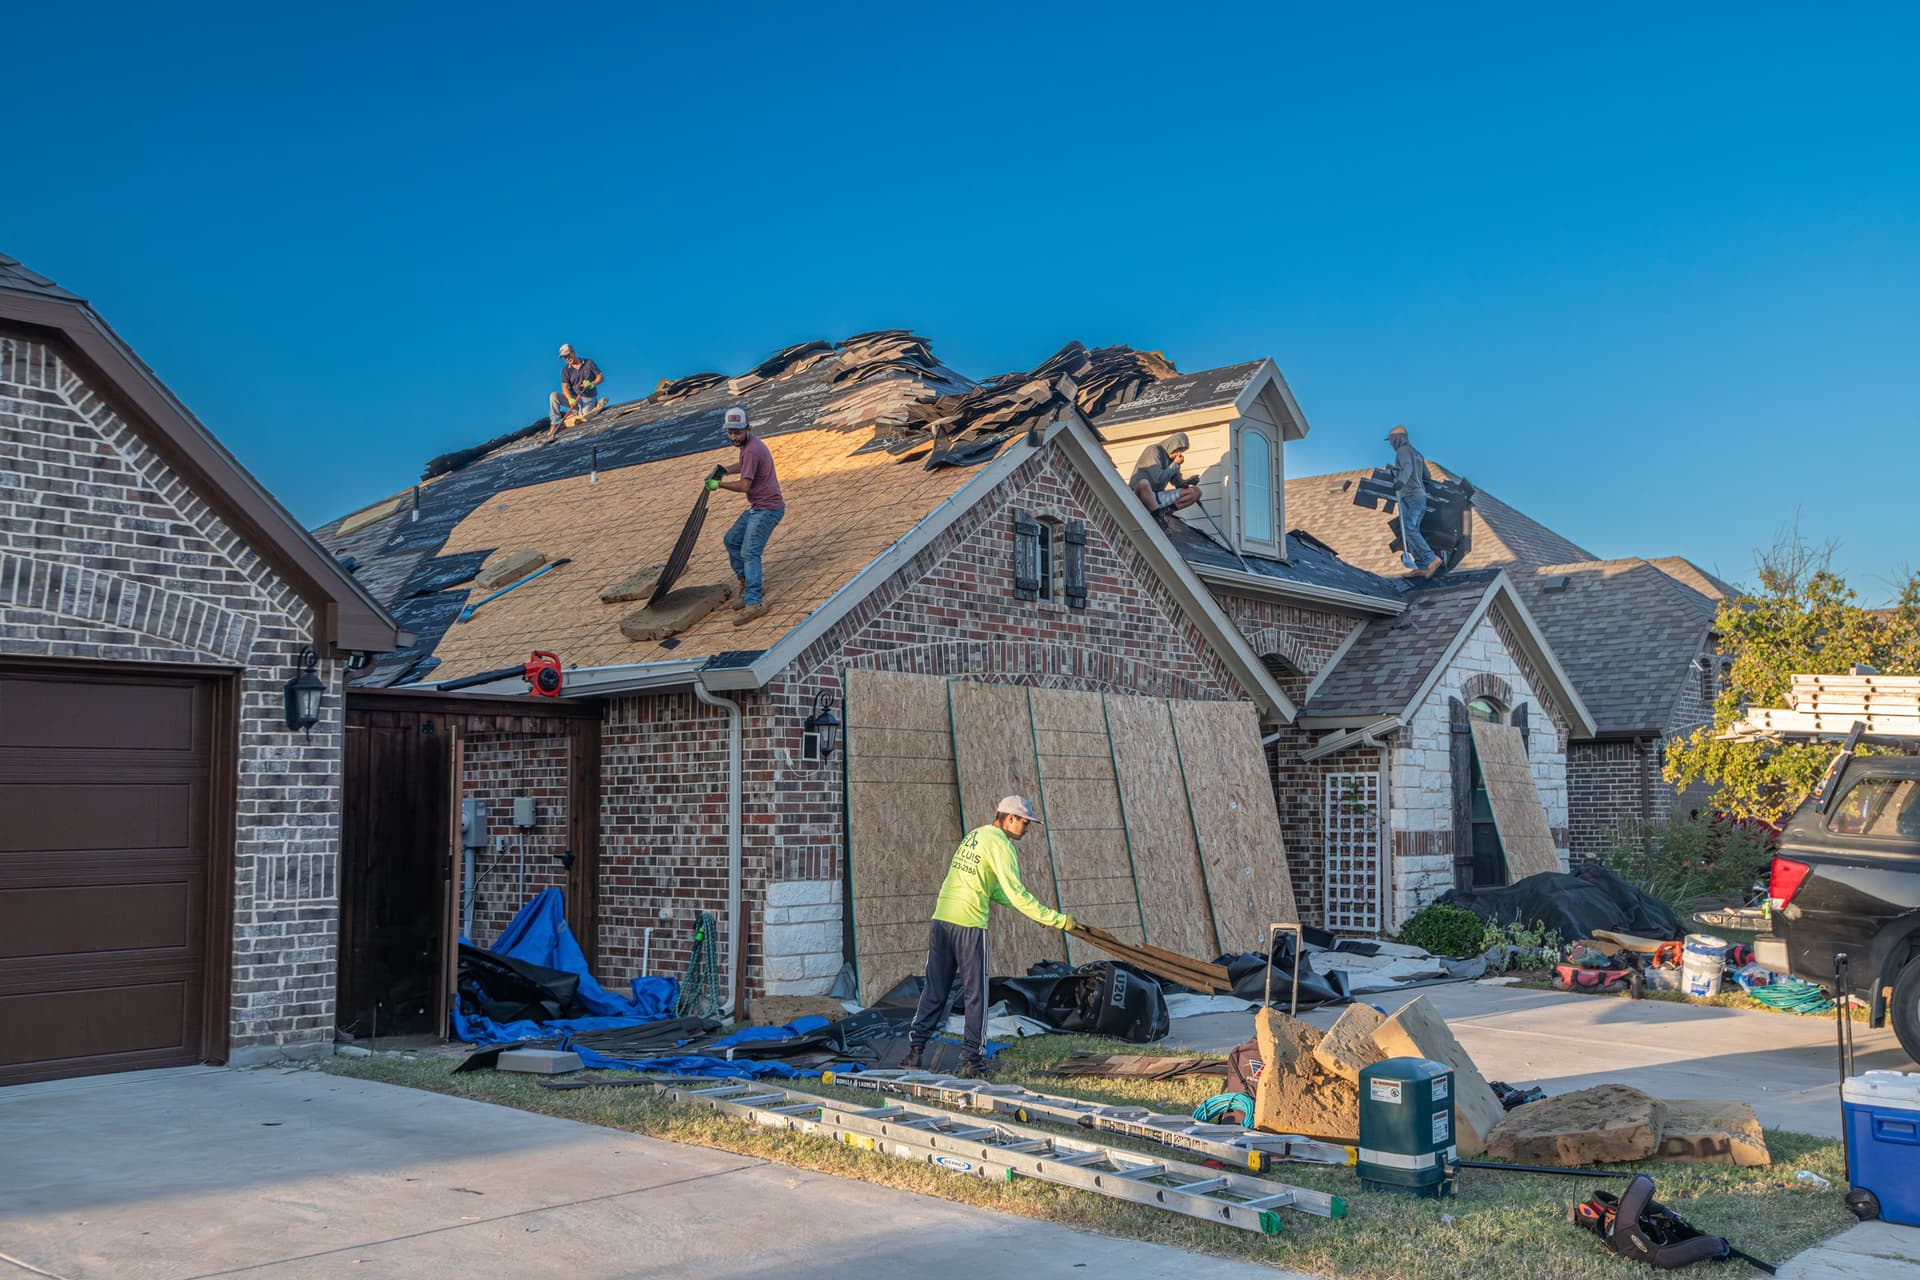
The carrier's estimate came in short. It leaves out the drip edge and starter, allows too little step flashing, and says nothing about the second layer and damaged decking you will find at tear-off. A supplement is how that work gets paid. It is a revised estimate that adds what the carrier missed, with the proof attached.
This guide shows how to supplement a roof claim on a full replacement, from the inspection to the final payment. A repair follows the same steps, with less to uncover at tear-off.
Keep one reader in mind throughout: the desk adjuster who approves the supplement, often without ever standing on the roof. Every line has to show that adjuster what is missing, why it is owed, and what proves it.
How to supplement a roof claim: the eight steps
A replacement gives you two chances to supplement. The first comes before production, for what the carrier's estimate missed. The second comes with your invoice, for what tear-off revealed. Steps 1 through 6 lead to the first supplement and steps 7 and 8 to the second. Each step builds the evidence the next one needs.
Step 1: Inspect the roof
Everything in a supplement traces back to the inspection. Frontera's guided inspections walk a crew through it on a phone. The Field Guide's roof inspection checklist and storm and hail damage inspection guide cover what to look for and how to tie the damage to the storm.
Capture more than you think you will need. Photograph every slope, edge, valley, layer, and penetration, and keep each photo dated and tied to the slope it shows. Circle hail hits and other damage in chalk before you shoot, so the adjuster's eye goes straight to it.
Start with a measurement report for the quantities. Where access is safe, inspect the roof and attic to record what the report cannot see, such as the number of layers, soft spots, flashing details, penetrations, and decking type. Note spaced sheathing in particular. Where the report looks wrong, check it by hand.
If the homeowner wants you at the adjuster's inspection, be there. The damage you found is then seen on the roof rather than argued about later.
Step 2: Read the carrier's estimate
Before you compare line items, check five things that decide what every line is worth. A mistake in any of them underprices the whole estimate at once.
- Repair or replacement. If the carrier paid for a repair, or for only some slopes, and the roof needs replacing, settle that first. No line item matters until it is settled. At a re-inspection, bring evidence that the roof cannot be repaired, such as brittle shingles or a discontinued product. Some states also have a matching rule that the homeowner can raise.
- Price list. Xactimate prices are set by area and updated at least monthly. Note which area and month the carrier used, especially when the work happens long after the loss.
- Waste. Xactimate adds the waste percentage to the measured quantity on the shingle line, so it sets how many squares the estimate pays for. Check it against the waste your measurements support.
- Overhead and profit. Check whether the carrier applied it and, in Xactimate desktop, which lines it left off. Xactware leaves the amount "up to the discretion of the estimator." The "three trades" rule (O&P only when three or more trades are involved) is a rule of thumb, not law. O&P pays for a general contractor's coordination and oversight, so name the trades you are coordinating, such as gutters, siding, and paint.
- Sales tax. The state decides what is taxed, most often materials only, and local rates vary. Xactimate suggests a tax jurisdiction from the loss ZIP code. One ZIP can carry several options, so check the one the carrier chose.
Not every estimate includes O&P or tax. Where your supplement handles either one differently from the carrier's estimate, say why.
Step 3: Find the gaps
Now compare the carrier's estimate with your scope, line by line. Start from the carrier's price list and line items so the real differences stand out. Gaps come in four kinds:
- Missing items. Check especially for starter, ridge cap, drip edge, valley metal, step flashing, ice and water barrier, pipe jacks and vents, the permit, detach-and-reset items, and steep and high charges.
- Wrong line items. Examples are a 3-tab shingle priced for a laminated roof, or detach-and-reset for something that cannot be reused, such as step flashing set behind brick. Swap in the right item and say why.
- Short quantities. Where the carrier's quantities fall below yours, your measurement report, hand measurements, and photos decide it.
- Low prices. Where a unit price is below your cost, attach invoices or supplier quotes, or ask for the price list to be updated to the month of the work.
Step 4: Write each line so it is easy to approve
What do you need to include in a roofing supplement? Every line you add or change needs an F9 note, the line note in Xactimate. The note tells an adjuster who has never seen the roof what is missing, why it is owed, and where the proof is.
Here is one line both ways. The roof has no drip edge, and the carrier's estimate leaves it out. The quantities are illustrative.
Weak
Drip edge, 260 LF
Nothing shows why it is needed or where 260 came from, so it is easy to cut.
Strong
Drip edge, 260 LF
F9: Not in carrier estimate. [Jurisdiction] enforces the [edition] IRC. R905.2.8.5 requires drip edge at eaves and rake edges of shingle roofs. The existing roof predates that requirement and has none at the eaves or rakes (photos 14 to 17). Quantity: 160 LF of eaves plus 100 LF of rakes, from page 2 of the measurement report. Code item; citation attached.
Desk adjusters often work from the estimate without opening the attachments, so the F9 note has to make the case on its own. The photos, the report page, and the code section are the backup. They let the adjuster check every statement in a minute. Every kind of line follows the same pattern, with its own proof:
| Line type | Proof to attach |
|---|---|
| Missed damage | Dated photos of the item and the slope, with the damage marked in chalk |
| Quantities | A measurement report or hand measurements that match the photos |
| Code items | The code section, the edition the jurisdiction enforces, and any local amendment |
| Manufacturer requirements | The installation instruction, with product name and document number |
Step 5: Add code upgrade items
Some lines are owed not because the storm damaged them, but because code requires them once the roof is replaced. Drip edge, ice barrier where the climate calls for it, and solid decking are the common ones. The IRC requires asphalt shingles to be fastened to a solidly sheathed deck. Spaced sheathing under an old shake roof therefore needs new sheathing over it.
The second layer on a two-layer roof is a removal line. Under the IRC, a roof replacement removes every existing layer down to the deck. If the carrier priced tear-off of one layer, add removal of the second as its own line. If the carrier scoped a new roof over the old one, cite the IRC rule against re-covering two or more layers.
Cite the edition your jurisdiction enforces, with any local amendment, not the newest IRC. That matters for the drip edge line, because a few states amend the code to require drip edge only where the shingle manufacturer does. Where the IRC is adopted, R905.1 also makes the manufacturer's required installation steps code items.
A code requirement shows that an item is necessary. It does not show which part of the policy pays for it, which is why the drip edge note above says "code item" and stops there.
Code costs beyond replacing what was there usually fall under the policy's ordinance-or-law coverage, which pays once the cost is incurred. On the HO 3, that is up to 10% of the Coverage A limit, as additional insurance, for the part of the building a covered peril damaged. The commercial CP 00 10 includes a smaller amount, the lesser of $10,000 or 5% of the building limit. The CP 04 05 endorsement can add more (see the ordinance or law guide).
Step 6: Send the first supplement before production
Send everything from steps 2 through 5 as one revised estimate with its F9 notes. Attach the proof, a one-page summary of each added or changed line and its amount, and the homeowner's signed authorization. Don't give the adjuster a reason to say no. A complete packet can be decided in one pass, while a partial one invites another round of questions.
Send it as early as you can. An approved scope before production means everyone knows what the job pays. You do not have to wait for approval to order materials or schedule the crew, though. Anything still open when the work starts goes on the final supplement. If the homeowner needs customer financing, agree on payment terms before work starts.
In the same message, say how you will handle what you cannot see yet. At tear-off, you will photograph and count any damaged decking and extra layers. You will replace what has to be replaced to dry the roof in, and supplement it with the photos.
Step 7: Document what tear-off uncovers
Once the roof is on, your tear-off photos are the only evidence. As each layer comes off, photograph it and the exposed decking. Mark each damaged sheet so the count shows in the photos. Replace it, dry in, and report what you found promptly.
If you find something major, call the adjuster before you replace it and offer a same-day re-inspection or video call. Major finds include rotted framing, a full re-deck, or a hidden layer across the whole roof. Tarp or dry in what is open while you wait.
Decking needs more than a sheet count, because policies exclude wear, rot, and deterioration. Show that the storm damaged the sheets. Where the decking is spaced or rotted instead, document the code section that requires a solid deck under the new shingles. Then supplement it as a code item, as in step 5.
Step 8: Send the final supplement and release the depreciation
When the roof is done, send the final supplement with your invoice. Include the tear-off findings at as-built quantities, completion photos, and a certificate of completion.
Under the HO 3, the carrier pays actual cash value until the repair is complete, except on small losses. It can release recoverable depreciation after the homeowner meets the policy's repair and documentation conditions. A homeowner who takes actual cash value first must tell the carrier within 180 days of the date of loss that they intend to repair or replace (see ACV vs. RCV). Give the homeowner the invoice and completion photos for that request, and follow up on the supplement until it is decided.
If the supplement is denied
A denial goes to the homeowner, because the claim is theirs. Your part is to support your own estimate. Ask the homeowner to request the reasons in writing. State claim-handling rules generally require the carrier to explain a denial or a reduced offer.
When the reasons are about your estimate's scope, quantities, or prices, answer them with documentation.
| Reason given | What answers it |
|---|---|
| Quantity does not match | The measurement report, any hand measurements, and photos that show the measured areas |
| Included in waste | Starter and ridge cap are separate materials with their own labor, so show each as its own line with a measured quantity |
| Price too high | Invoices, supplier quotes, or the price list for the month of the work |
| O&P not warranted | The trades you coordinated and the oversight they required |
When the reason is coverage, the question is between the homeowner and the carrier. Wear and tear is one example, and so is a code item the carrier says the policy does not pay. Give the homeowner your photos and code citations. In most states, arguing coverage on the homeowner's behalf takes a public adjuster license.
If the desk review stalls, the homeowner can ask for a re-inspection of anything still visible, or a review by the adjuster's supervisor. If the disagreement continues, these options are the homeowner's to use:
- Appraisal, when the dispute is only about the amount of loss. Either side can demand it, and each pays its own appraiser (see the appraisal guide).
- A licensed public adjuster or an attorney.
Deadlines keep running while this plays out. The HO 3 requires a lawsuit within two years of the date of loss unless state law says otherwise. A state can also set its own notice deadline for supplemental claims.
FAQ
What are supplements in roofing?
Roofing supplements are requests to revise the carrier's estimate after the first adjustment. They add items the carrier missed, items code requires, or damage found once work began. They usually go in under the original claim.
Can a roofer talk to the insurance adjuster about a supplement?
Yes, about your own estimate, but not as the homeowner's representative. In most states only a licensed public adjuster or an attorney can negotiate a claim for the homeowner. The state rules are listed in References. Carriers usually want the homeowner's written authorization before discussing the claim with you.
Do you need Xactimate to write a roofing supplement?
No. The standard HO 3 form names no estimating program. Still, roof supplements written on the carrier's platform and price list are the quickest to check. A PDF estimate from other software can be converted to ESX.
How long does supplement approval take?
There is no single clock. The NAIC model regulation, which states can adopt, gives a carrier 21 days after receiving proof of loss to accept or deny, or to explain why it needs more time. The HO 3 then pays 60 days after proof of loss once the amount is agreed, set by an appraisal award, or decided by a court. If the carrier asks for a sworn proof of loss, the homeowner has 60 days to send it.
Roof estimates, supplements, and Frontera
Frontera's estimating software writes roof estimates and supplements the way this guide describes. It builds complete Xactimate-formatted line items with F9 notes that cite the code section and the state adoption behind each requirement. It collects the photos, measurements, and code references for every line into one evidence packet. It exports ESX for Xactimate or PDF.
Frontera's guided inspections run on the phone your crews already carry. Standardized forms walk the inspection step by step. Photos land against the slope or elevation they belong to, then feed straight into the estimate. Frontera's Estimate Comparison lines up the carrier's estimate against yours, line by line, so every gap in scope, quantity, and price from step 3 is in front of you.
Frontera is built for roofing contractors and public adjusters who prepare the documentation. It does not communicate with carriers on your behalf.
References
- ISO Form HO 00 03 03 22, Homeowners 3 – Special Form: Section I Perils Insured Against (wear and tear, deterioration), Additional Coverage E.10 Ordinance or Law, and Section I Conditions (Duties After Loss, Loss Settlement, Appraisal, Suit Against Us, Loss Payment)
- ISO Form CP 00 10 10 12, Building and Personal Property Coverage Form: Increased Cost of Construction, Loss Conditions, and Replacement Cost optional coverage
- ISO Form CP 04 05 09 17, Ordinance or Law Coverage
- International Residential Code R905.1, R905.2.1, and R905.2.8.5 (2021 IRC, ICC Digital Codes); ICC, Significant Changes to the 2012 IRC, R905.2.8.5 Roof Drip Edge
- Re-roofing, IRC R908.3 and R908.3.1.1: City of Des Moines, "Residential Asphalt Shingle Requirements" (quotes IRC R908.3.1.1), City of East Point, Georgia, 2018 IRC residential re-roof guide, and City of Mission, Kansas, "Permit requirements for: Roofing" (2018 IRC R908.3, removal down to the deck)
- State drip edge variations: S.C. Code Regs. 8-1228 and Prince William County, Virginia, "Roof Replacements"
- Xactware Help, "Attach or delete notes, images, or sound files to a line item in X1" (checked October 2026)
- Xactware, "Pricing Methodology Summary"; Xactware Help, "Auto waste calculation workflow"; Xactware Help, "Add O&P in Xactimate online"; and Xactware Help, "Add Overhead and Profit to an item" (checked October 2026)
- Verisk, "Overhead and Profit Settings on Sales Tax" and Xactware Help, "Tax jurisdictions of the same percentage" (checked October 2026)
- United Policyholders, "Payment of Overhead and Profit"
- NAIC, Unfair Claims Settlement Practices Act (MDL-900), § 4.L, and Unfair Property/Casualty Claims Settlement Practices Model Regulation (MDL-902), §§ 6, 7, and 9.A
- Chip Merlin, "What is a Supplemental Claim?", Property Insurance Coverage Law Blog
- State rules. Florida defines supplemental claims and sets their notice deadline in Fla. Stat. § 627.70132. Texas sets claim-handling deadlines in Tex. Ins. Code ch. 542, subch. B.
- Public adjuster licensing. As of 2023, all but four states license public adjusters (Joseph S. Harrington, "Fulfilling the Coverage You Sell," Rough Notes). State rules on what contractors may do include Texas, Tex. Ins. Code § 4102.163 and TDI Bulletin B-0008-24; Florida, Fla. Stat. § 489.147; Minnesota, Minn. Stat. § 325E.66; and Iowa, Iowa Insurance Division consent order (December 2024).
This article is for educational purposes and does not constitute legal advice. Policy forms and state law change; confirm the issued policy and current rules for each claim.