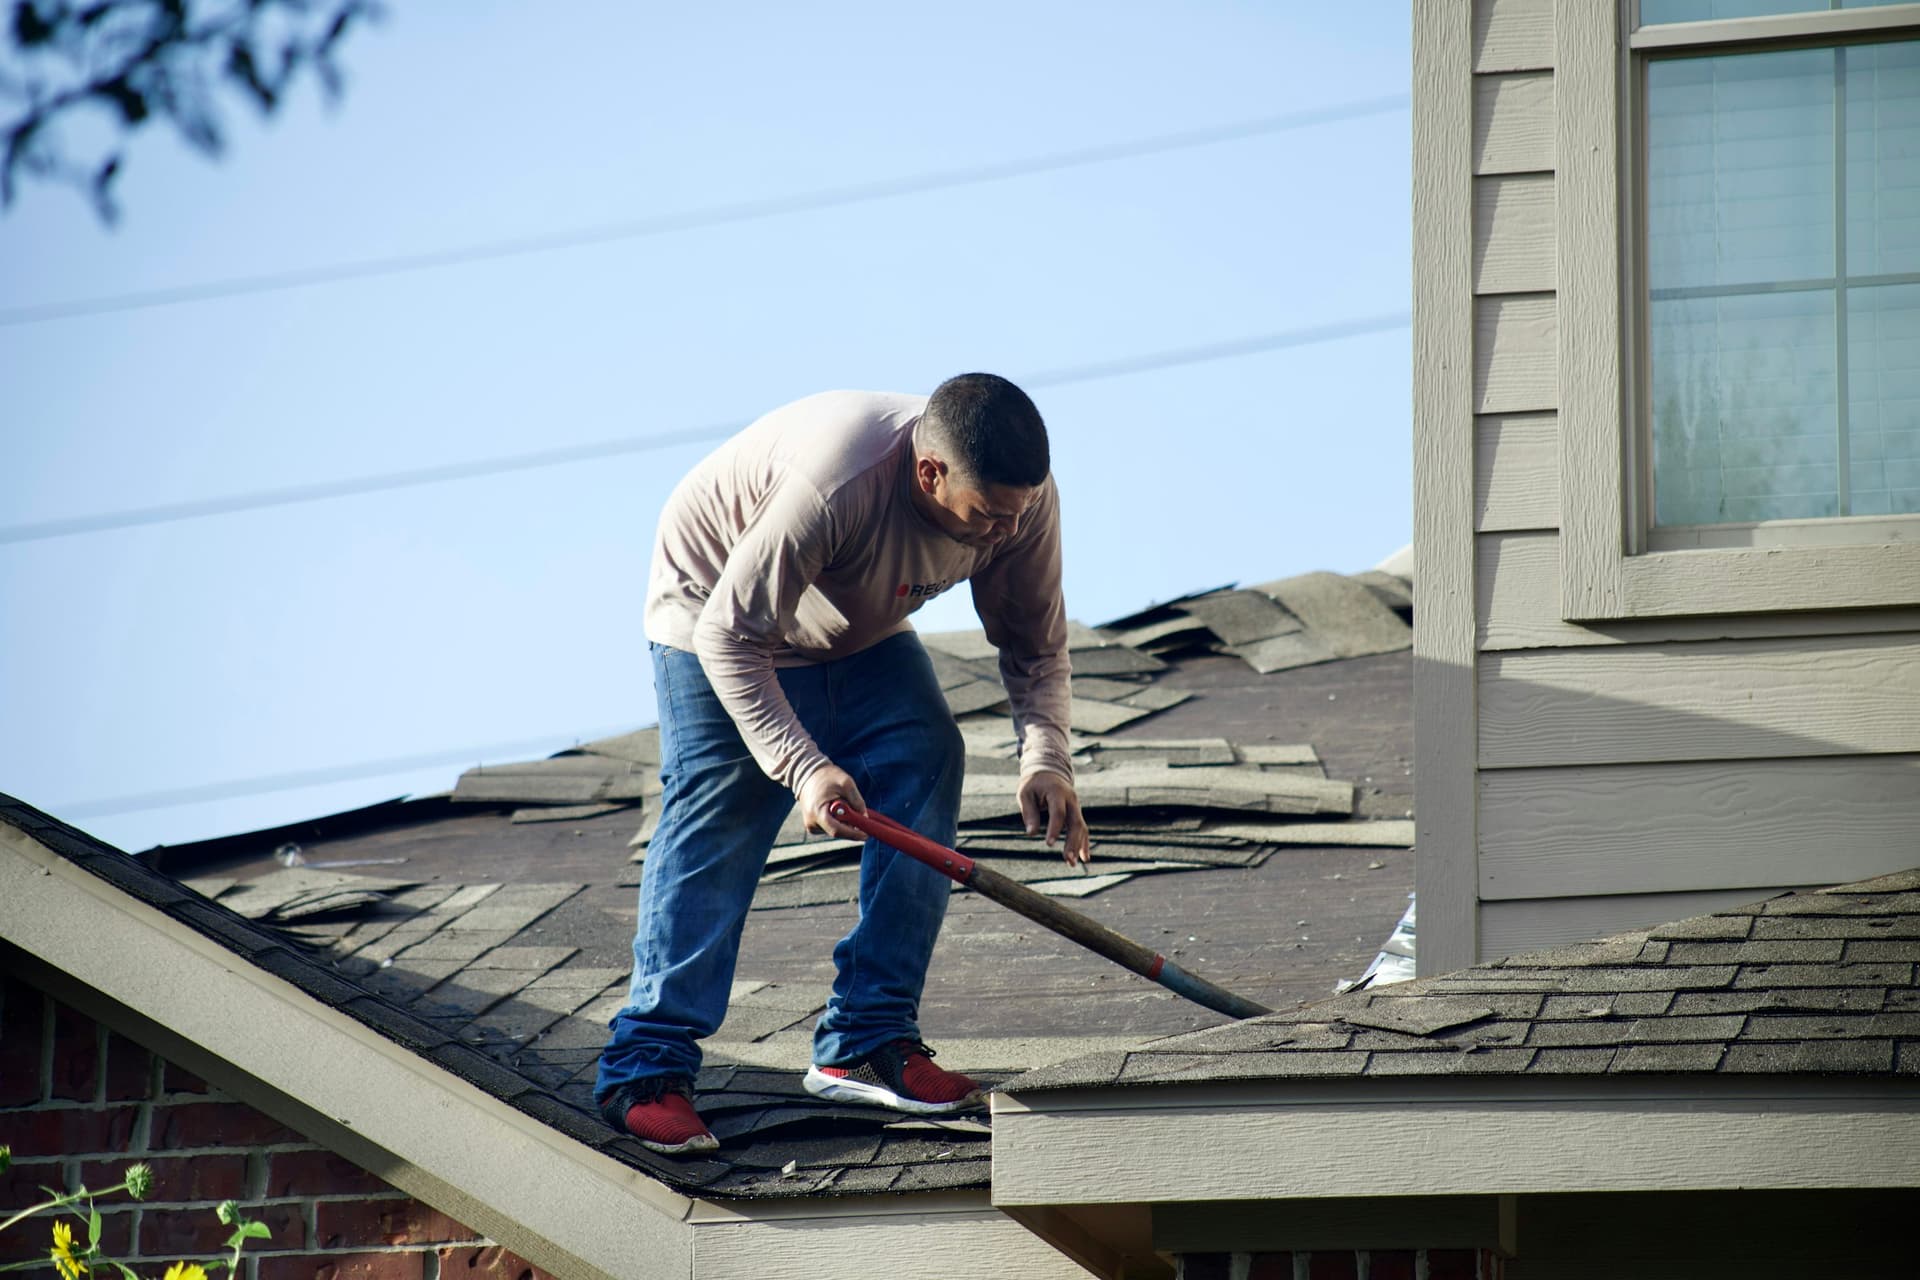
A homeowner likes your bid but can't write an $18,000 check. Customer financing for contractors solves that: your customer borrows from a lender to pay for the work.
"Free" financing always has a payer. You pay through a dealer fee or subscription, or the homeowner pays through the lender's rate, so the real choice is who pays and when the money reaches you. Below are seven programs for roofing and restoration owners, how to choose between them, and how financing fits an insurance job.
Customer financing for contractors: seven programs
These seven programs finance home improvement work and are making new loans. They are listed alphabetically, not ranked as the best contractor financing companies.
Some names have changed hands. EnerBank is now Regions, Truist owns Service Finance, and a Sixth Street-led group bought GreenSky in 2024. Mosaic filed for Chapter 11 in June 2025 and is not listed.
Acorn Finance
A marketplace that shows your customer personal-loan offers from 20+ lenders.
- Cost: None to you; lenders pay Acorn when a loan closes (checked October 2026).
- Loan size: $1,000 to $100,000; rates vary by lender.
- Pays you: The customer pays you from the loan, which Acorn says can fund 1 to 2 business days after approval.
- Good fit for: A no-cost option, and AccuLynx users, where it runs as AccuFi.
- Acorn Finance
GreenSky
Home improvement loans from partner banks, applied for through member contractors.
- Cost: Not published (checked October 2026).
- Loan size: Up to $100,000 over 5 to 12 years (NerdWallet).
- Pays you: In about a day (NerdWallet).
- Good fit for: Deferred-interest promotions.
- GreenSky
Hearth
Contractor software with 18+ lenders built into your quotes. Hearth is a broker, not a lender.
- Cost: annual subscription, quoted by service level; Hearth describes a typical $2,000 to $6,000 yearly investment, with no per-loan dealer fee (checked October 2026).
- Loan size: $1,000 to $250,000; credit scores down to 550.
- Pays you: The customer pays you from loan proceeds; Hearth says funding can arrive in as little as 24 hours after approval.
- Good fit for: Enough financed volume that a flat cost beats a per-job fee.
- Hearth financing

Regions (formerly EnerBank)
A bank's home improvement loans, offered through contractors, roofing included.
- Cost: Dealer fee on many products, disclosed in advance; no membership fees (checked October 2026).
- Loan size: Not published.
- Pays you: Usually within 24 hours after the homeowner authorizes payment.
- Good fit for: A bank program with a relationship manager.
- Regions contractor financing
Service Finance
A Truist-owned sales finance company that finances roofing among 500+ products.
- Cost: Not published (checked October 2026).
- Loan size: Not published.
- Pays you: By ACH after completion and the borrower's authorization.
- Good fit for: ServiceTitan users, whose technicians can present its payment options in the field.
- Service Finance
Synchrony
The Synchrony Project Card, a reusable homeowner credit card with 6 to 132 months of special financing at participating contractors.
- Cost: Not published (checked October 2026).
- Loan size: Not published.
- Pays you: Not published.
- Good fit for: Repeat customers; its page doesn't list roofing, so confirm it qualifies.
- Synchrony for home improvement
Wisetack
Per-transaction financing sent by text or invoice link.
- Cost: 3.9% per transaction (its published rate), no subscription (checked October 2026); ask what extended 0% plans cost.
- Loan size: $500 to $65,000; JobNimbus lists $25,000, so check your CRM's cap.
- Pays you: Within 3 business days after the customer confirms.
- Good fit for: Quotes sent from JobNimbus, Jobber, Housecall Pro, or another integrated tool.
- Wisetack
How to choose a financing program
Four questions decide whether a program fits your business.
Who pays for it? The programs that publish how they charge use one of three models. With a dealer fee, the lender keeps a percentage of each financed job, as Wisetack and Regions do. With a subscription, you pay a flat yearly fee and nothing per loan, as with Hearth. With a lender-paid marketplace such as Acorn, lenders pay the platform and the homeowner pays the lender's rate, so it costs you nothing.
A dealer fee comes out of your payout, while the homeowner still owes the full contract price. At Wisetack's published 3.9%, the fee on an $18,000 roof is $702. The fee is often what pays for the same-as-cash and low-rate promotions homeowners like. A subscription works the other way: it stays flat as volume grows. At that 3.9%, Hearth's stated $2,000 to $6,000 annual range equals the fee on about $51,000 to $154,000 of financed work. Its subscription also includes software, so compare the services as well as the fee. Get a current quote and every fee in writing, including minimums and inactivity charges.
If a promotion uses deferred interest, as some GreenSky and Service Finance plans do, explain it at signing. If any balance remains when the promotion ends, the homeowner owes all the interest that accrued during it.
When do you get paid? Direct-to-contractor programs may wait for completion or the homeowner's payment authorization. You carry the job until then, and an open punch-list item can hold up the whole check. Acorn and Hearth fund the homeowner, who then pays you, so agree on deposits and progress payments as you would on a cash job.
Who gets approved? Approval floors vary. JobNimbus says Wisetack approves from the mid-500s, while some lenders stop around 660. Ask whether there's a waterfall, which passes a declined applicant to a second lender. Also ask how long an approval lasts, because a storm backlog can push the install past it.
Does it fit your tools? Wisetack runs inside JobNimbus, Acorn inside AccuLynx, and Service Finance inside ServiceTitan.
Federal rules reach you even though the loan is the homeowner's. Three matter most:
- Let only the homeowner apply. Approval links go to the homeowner's phone or email, never a rep's. In 2021 the CFPB ordered GreenSky to pay a $2.5 million penalty over applications consumers never authorized, with merchants at fault in at least 1,600 cases.
- Offer it to everyone the same way. If you regularly refer applicants, Regulation B treats you as a creditor for its bans on discrimination and on discouraging applications.
- Charge one price, cash or financed. Under Regulation Z, a higher price for financed customers can count as a finance charge. On retail jobs, build the expected fee into your standard price.
Cancellation windows and the FTC Holder Rule also apply, so check both with your lender.
Financing on an insurance job
On a claim job, financing covers two things: the homeowner's upgrade and the wait for money the carrier is holding.
The first is the homeowner's upgrade. If the carrier pays for architectural shingles and the homeowner wants standing-seam metal, finance the agreed difference, in writing, before tear-off. Code-required items aren't upgrades. They belong in your estimate with the code citation, and whether the policy pays for them depends on its ordinance-or-law coverage.
The second is the wait. Until the repair is complete, the HO 3 pays only actual cash value, except on small losses, and the mortgage company may hold the check (see ACV vs. RCV). Finance only what is held, and count only depreciation the carrier's estimate shows as recoverable, because the loan is owed whatever the carrier finally pays. If the roof is on an actual cash value or roof-schedule endorsement, no held payment is coming. Some loans, such as Service Finance's, can't grow after funding, so extra work takes a new application.
The dealer fee on covered work comes out of your margin, not the estimate.
The deductible is not a gap you fill. It's the homeowner's to pay, and some states make it illegal for a contractor paid from claim proceeds to promise, waive, or rebate it.
FAQ
Is there free customer financing for contractors?
Yes, if free means free to you. Acorn costs you nothing because lenders pay Acorn and the homeowner pays the lender's rate. Hearth has no dealer fee but charges a subscription.
Does offering financing affect my customer's credit?
Prequalification uses a soft pull where the program offers it. Proceeding with financing may involve a hard credit check, and the loan and repayment history can affect credit. Confirm the lender's process before the homeowner proceeds.
Who takes the loss if a financed customer stops paying?
Usually the lender, which underwrites and carries the loan. Your dealer agreement's chargeback terms say when a lender can take a payout back, and you still answer for the work.
References
- Acorn Finance, home page and FAQ, and AccuLynx, AccuFi integration (checked October 2026)
- GreenSky: NerdWallet, "GreenSky Review" (2026), and Sixth Street, "GreenSky Announces Completion of Acquisition by Sixth Street-Led Consortium" (2024)
- Hearth, "Contractor Financing for Your Customers", Pricing, "Hearth vs Acorn Finance", and "What Is a Dealer Fee?" (checked October 2026)
- Regions Bank, Contractor financing and Home Improvement Financing (checked October 2026), and Regions Financial, Form 8-K on the EnerBank acquisition (2021)
- Service Finance, What We Finance and FAQs (checked October 2026); ServiceTitan, Service Finance Integration; and Truist, acquisition announcement (2021) and fourth quarter 2021 results (2022)
- Synchrony, Offer Financing for Home Improvement and Synchrony Project Card (checked October 2026)
- Wisetack, home page, consumer FAQs, and "Wisetack vs. Regions", and JobNimbus, Wisetack integration (checked October 2026)
- Mosaic: Solar Power World, "Solar finance platform Mosaic files for bankruptcy" (2025)
- FTL Finance, "How to Choose a Customer Financing Company" (2026)
- Federal Trade Commission, Holder Rule, 16 CFR 433.2, and Cooling-Off Rule, 16 CFR 429.0 and 429.1
- Consumer Financial Protection Bureau, Regulation B, 12 CFR 1002.2; Regulation Z, 12 CFR 1026.4 and 1026.23; and "CFPB Takes Action Against Fintech Company GreenSky" (2021)
- ISO Form HO 00 03 03 22, Homeowners 3 – Special Form, Section I Conditions B, D, and L
- Deductible laws: Texas, Tex. Bus. & Com. Code § 27.02 and Tex. Ins. Code § 707.002; Colorado, C.R.S. § 6-22-105
- Home Improvement Research Institute, "New Contractor Data: Financing, Warranties, and Customer Relationships" (2021)
- Hearth reviews: Software Finder and ComplaintsBoard (checked October 2026)
This article is for educational purposes and is not legal or financial advice. Provider terms change; confirm current terms with each provider before you sign.